First Steps After Storm Damage
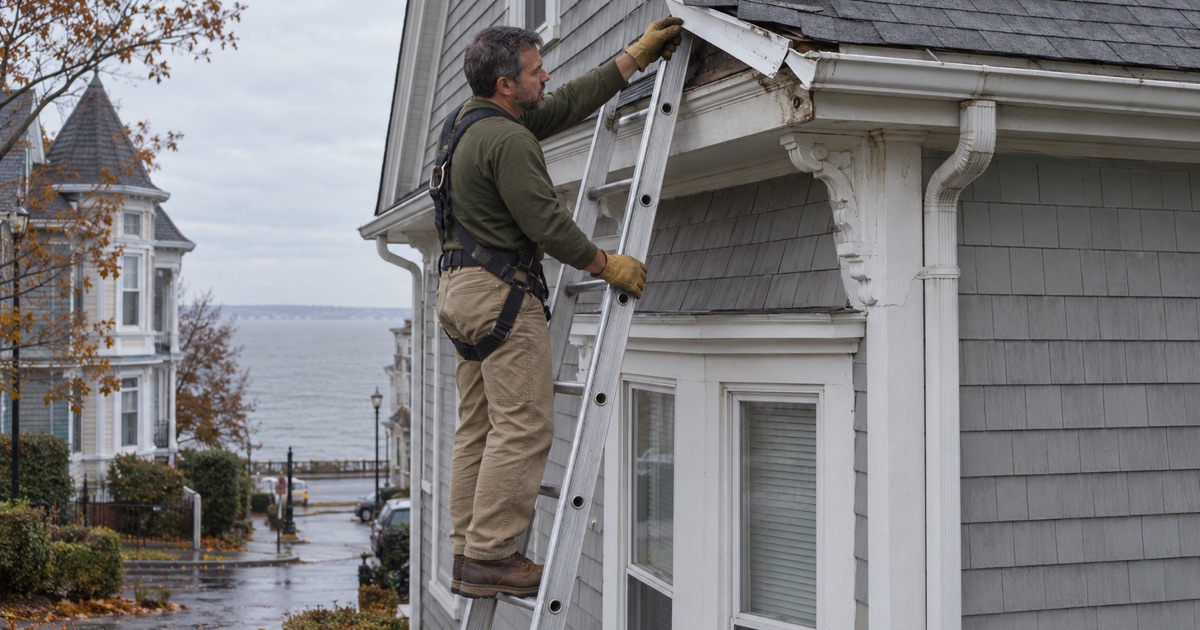
After a storm, photograph the damage inside and out, make only the temporary repairs needed to stop more water, and keep every receipt. We document what we find on the roof with photos and a written description for your own claim. Those records and receipts are what your insurer will ask to see.
How a Homeowners Roof Claim Works in New Jersey
You report the loss to your insurer, an adjuster inspects, and the company decides what the policy covers. The Department of Banking and Insurance’s storm guidance notes that it sometimes helps to have your contractor speak directly with the adjuster, and when you ask, our crew will meet the adjuster on site. The claim and every decision in it stay yours.
Wear and Tear Versus Storm Damage
Policies generally cover sudden damage from wind or a falling tree, not a roof that has worn out with age. Adjusters look for creased or missing shingles, fresh impact marks and torn flashing that line up with a dated storm, and they deny claims where the damage looks gradual. Our photos and notes put what we saw in front of the adjuster.
Public Adjusters and Who Can Negotiate a Claim
Under the Public Adjusters’ Licensing Act, N.J.S.A. 17:22B, anyone paid to negotiate a property claim for an owner must be a licensed public adjuster. We are roofers: we document damage and meet the adjuster when asked, but we never negotiate or settle a claim for you. If you want representation, a licensed public adjuster is the person to hire.
Flood Zones and the 50 Percent Rule
Parts of Perth Amboy’s shoreline are mapped in FEMA high-risk flood zones; the Ferry Slip at the foot of Smith Street reads zone VE, with wave action. In zones VE and AE, repairs that reach 50 percent of a building’s market value can trigger the substantial damage and substantial improvement rules, which require the building to meet current flood standards. If your house is in a mapped zone, check with the city before a large storm repair.
Perth Amboy’s Home Improvement Program
The city’s Home Improvement Program offers eligible owners up to $25,000 as a 0 percent, ten-year forgivable loan, and roofs are among the eligible repairs. Income limits and other conditions are set by the program, not by us. What we provide is the written roof scope you can submit with your application.
Sales Tax on a New Roof Versus a Repair
New Jersey treats a roof repair as taxable, while a complete new roof is an exempt capital improvement documented on Form ST-8, the Certificate of Exempt Capital Improvement. Which treatment applies changes the bottom line. We note on the estimate whether your job is a repair or a capital improvement so there is no confusion at the end.
What a Roof Replacement Costs
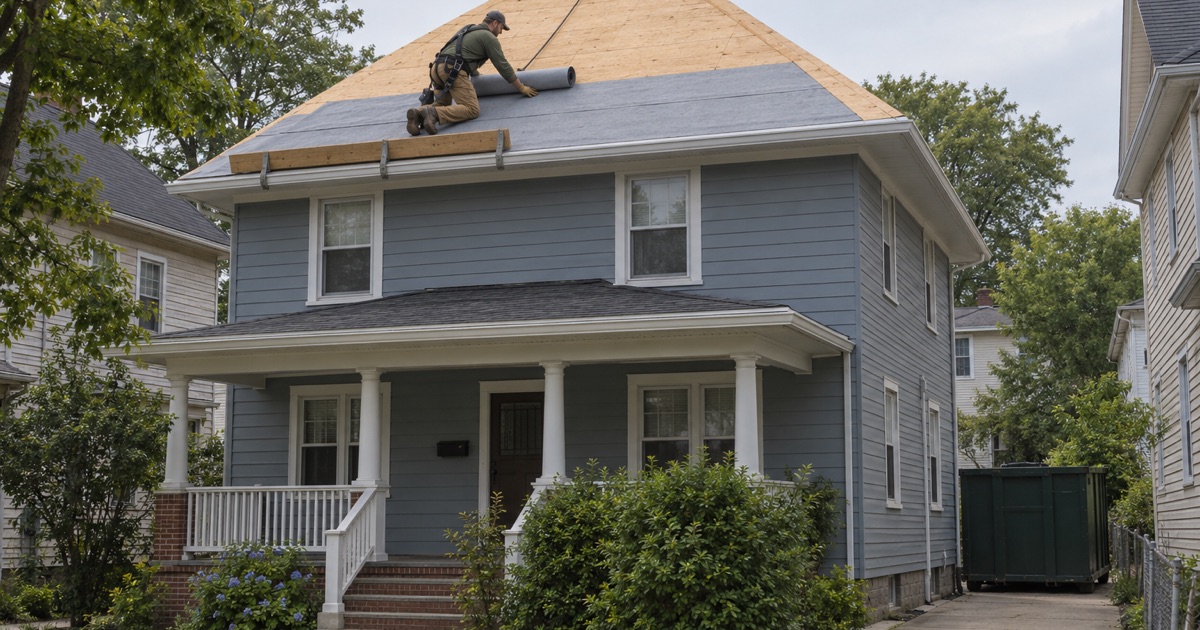
Price depends on roof size, pitch, the number of layers coming off, how much decking needs replacing, and the flashing, ventilation and gutter work included. Steep prewar gables and flat rear sections each add labor, and a third story adds staging. Because our scope lists each item separately, you can see which of those factors moves your price.
What a New Jersey Roofing Contract Has to Include
Home improvement contracts over $500 must be in writing and carry the three-business-day cancellation notice under N.J.S.A. 56:8-151, and contractors must be registered under the Contractors’ Business Registration Act. Our contracts are written to those rules, with the scope, price, start and finish dates and the per-sheet decking price spelled out. Look for each of those items before signing any roofing contract.